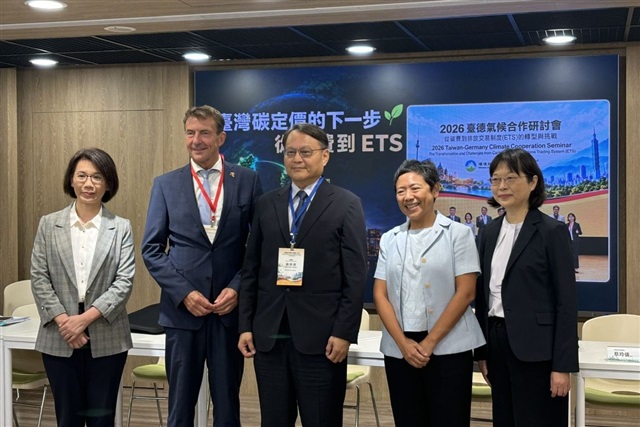
Taiwan intends to pilot an emissions trading scheme by end-2026, aiming to align semiconductor and tech manufacturers with international carbon systems, with policy advisers flagging design safeguards as critical.
The strategic significance sits far above Taiwan's borders. When the world's most concentrated cluster of advanced logic fabrication starts pricing carbon, the cost signal propagates downstream to everyone who buys leading-edge silicon. Chip fabs are energy-intensive by nature, and Taiwan's grid still leans heavily on fossil fuels. A domestic carbon price does two things at once: it partially pre-empts external mechanisms like the EU's carbon border adjustment, and it converts a diffuse ESG obligation into a hard operating expense that flows into wafer pricing. The three-safeguard framing an adviser raised matters because a poorly calibrated scheme risks either being too soft to change behavior or too aggressive to preserve competitiveness against Korean and US fabs operating under different carbon regimes.
The deeper shift is that carbon accounting is becoming a supply-chain governance problem, not an environmental one. Scope 3 emissions mean a fabless designer, a cloud provider, or a consumer-electronics brand now inherits the carbon intensity of its Taiwanese suppliers. Expect procurement teams to start demanding verified emissions data alongside yield and lead-time figures, and expect green-power sourcing to become a genuine differentiator in foundry allocation decisions.
For Japan, the implications are direct and underappreciated. Japanese firms are among the largest consumers of Taiwanese foundry capacity, so any carbon cost embedded in wafers lands squarely in the bill of materials for domestic device and automotive-semiconductor buyers. Japan's own GX (Green Transformation) agenda and its emerging carbon-pricing roadmap mean this is not a foreign problem to observe but a preview of pressures its own fabs, including new domestic advanced-node efforts, will face.
Japanese SIers and enterprise IT teams should read this as a demand signal. Carbon data management, emissions traceability across multi-tier supply chains, and integration of ESG reporting into ERP and procurement systems are becoming concrete implementation projects. The winners among local integrators will be those who treat carbon as a data-engineering and compliance-automation challenge, building the pipelines that turn regulatory obligation into auditable, board-ready reporting rather than one-off consulting decks.




