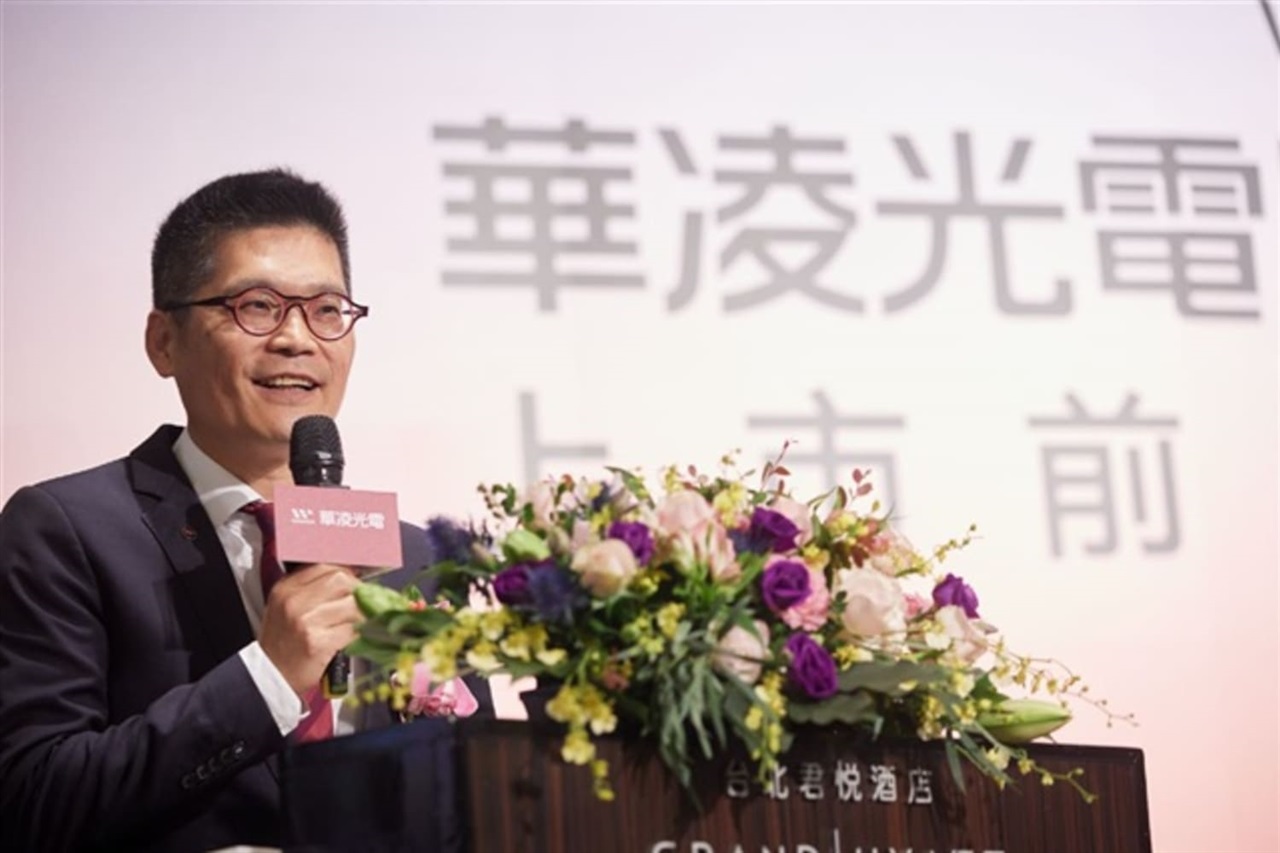
The headline story of AI infrastructure has been about the marquee layers: Nvidia silicon, hyperscaler data centers, and the debt and venture capital now flowing into the physical buildout. Winstar Display's expansion into AI applications points to the part of that story most executives underprice, the long tail of industrial components that populate every rack, test bench, and power system behind a data center. A display-module supplier projecting 30–40% AI-related order growth in 2026, with AI revenue share climbing from 3–4% toward 5%, is a small signal of a large pattern: capex at the top compounds into demand at layers few investors track.
The strategic read is that AI infrastructure is becoming a broad industrial cycle, not a narrow semiconductor trade. Power management, controllers, testing equipment, and human-machine interfaces all scale with facility count. That diffuses demand and cushions component makers that historically rode volatile consumer-electronics cycles. The risk is concentration and timing: orders extending into 2027 sound durable, but they hinge on hyperscaler capex holding through a higher-for-longer rate environment. If financing costs pressure the buildout, the long tail feels it last but hardest.
For Japan, this is the more actionable layer of the AI story than another frontier-model release. Japanese suppliers of displays, sensors, passives, and power components sit precisely in this diffusion zone, and the yen environment favors export-oriented industrial vendors positioned for data-center and factory-automation demand. The question for management teams is whether they reclassify AI-adjacent revenue as a strategic segment with its own roadmap, rather than burying it inside legacy industrial lines.
For SIers and domestic system builders, the implication is procurement and design. As AI data centers and edge testing environments scale in Japan, integrators that lock in qualified component supply and thermal, power, and interface expertise early will hold an advantage over those competing purely on labor. For enterprise dev and RPA teams, the takeaway is subtler: the physical buildout is what makes on-prem and edge inference economically viable, expanding where Japanese firms can deploy AI workloads without exporting sensitive data to foreign clouds. The component layer is quiet, but it is where a lot of Japan's AI upside actually lives.




