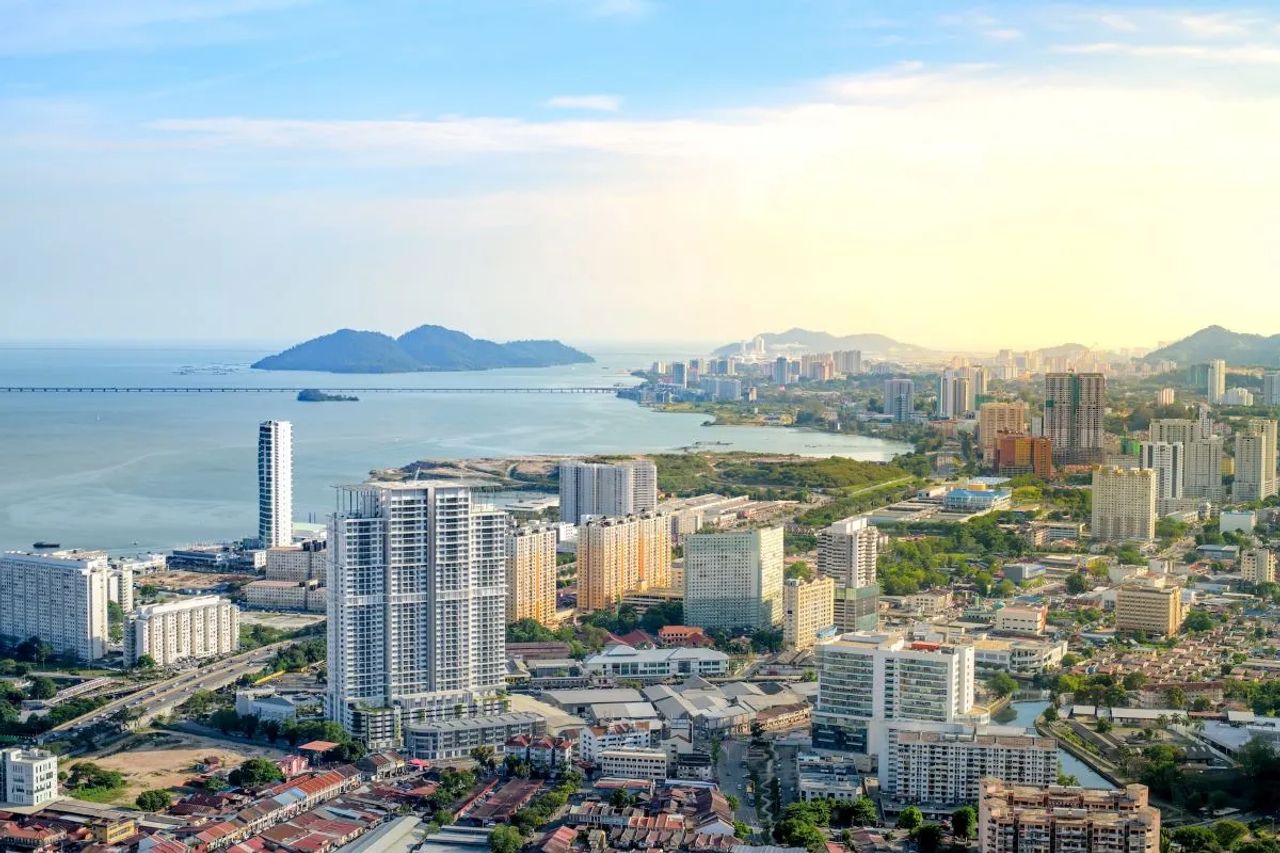
Malaysia, long the region's workhorse for outsourced assembly and testing, is now maneuvering to capture higher-value links in the chip supply chain rather than staying at the low-margin tail end.
The strategic logic is sound. As the industry's center of gravity shifts from raw transistor scaling to advanced packaging, chiplets, and heterogeneous integration, the back end of manufacturing is no longer an afterthought. It is where a growing share of performance gains and cost differentiation now lives. Malaysia enters this window with real assets: decades of packaging expertise clustered around Penang, an English-capable engineering workforce, and neutral positioning that appeals to firms de-risking away from single-country concentration. The constraints are equally real. Advanced packaging demands capital intensity, cleanroom sophistication, and design-adjacent talent that Malaysia does not yet own outright, and it will compete for the same skilled labor and equipment allocations as Taiwan, Singapore, and the reshoring push in the US and Japan.
Geopolitically, this is another data point in the slow rewiring of the chip map. Every credible alternative back-end node reduces the leverage of any single chokepoint, which buyers and governments increasingly treat as a security requirement rather than a cost line. The question is whether Malaysia can move fast enough to matter before capacity commitments elsewhere harden.
For Japan, the implication is more opportunity than threat, and it is worth naming precisely. Japan's semiconductor strength sits disproportionately in materials and equipment, the exact inputs a maturing packaging hub must import. Vendors of photoresists, bonding films, dicing and grinding tools, and inspection systems gain a growing, geographically diversified customer base as Malaysia scales up the stack. That diversification also matters for Japan's own resilience, spreading back-end dependence beyond Taiwan.
For Japanese chipmakers and fabless-leaning designers, a stronger regional packaging option offers a nearer, politically neutral alternative to routing everything through the most crowded nodes. For SIers and enterprise IT teams, the practical work is unglamorous but real: supply-chain visibility platforms, multi-country procurement and traceability systems, and ERP integrations that can model a more fragmented, multi-node sourcing reality. Firms that hardcoded a single-country assumption into their planning systems will feel the pain of re-architecting; those who build flexibility now turn Malaysia's rise into a procurement advantage rather than a migration scramble.




