Apple's first foldable device is shaping up to be as much a supply-chain story as a product one. The company's component value is set to concentrate heavily among South Korean vendors spanning displays, cameras, substrates, passives, and memory. The strategic signal is clear: a new form factor resets the bill of materials, and the vendors who own the hardest engineering problems capture the richest margins.
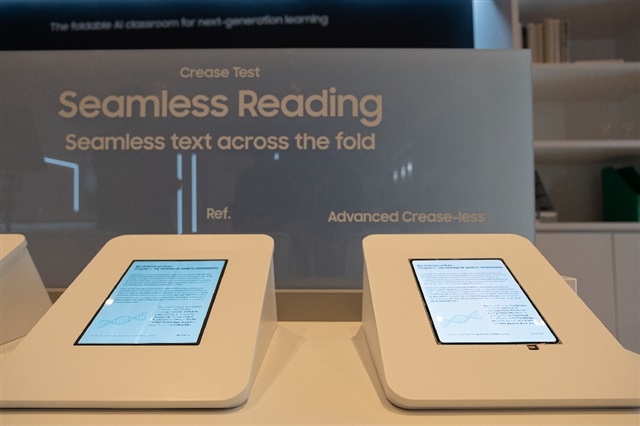
Folding introduces failure modes that flat phones never faced, including crease control, hinge fatigue, and ultra-thin flexible panels that survive years of bending. That difficulty is precisely why the value pools where it does. Flexible OLED and advanced substrate work are not commodities Apple can dual-source overnight, so early foldable economics reward the few suppliers with proven yields. For Apple, that means margin pressure and concentration risk on a premium halo product; for competing suppliers, it means the foldable era may harden an incumbency they cannot easily dislodge later.
The broader implication is that foldables extend, rather than disrupt, the existing display and memory hierarchy. A CEO transition and a marquee launch grab headlines, but the durable shift is which national supply bases get locked into the next decade of Apple hardware. Component nations that miss the first foldable wave risk being designed out of the category before it scales.
For Japan, this is the uncomfortable subtext. Japanese suppliers have long held valuable Apple sockets in areas like image sensors and passive components, and those positions are not automatically threatened by a foldable. But the flexible-display layer, where Japanese panel makers have struggled to match Korean scale and yield, is exactly where foldable value concentrates. If the category grows, Japan's component base could find its share of each iPhone shrinking as display-driven value rises.
For Japanese electronics firms, SIers, and manufacturing-tech teams, the takeaway is to stop competing on finished-panel scale and move up into adjacent, defensible niches: hinge mechanics, precision materials, inspection and yield-analytics systems, and the automation software that governs high-reject-rate flexible production. That is where domestic engineering depth still translates into pricing power. The lesson from this launch is that form-factor transitions redraw supplier maps quickly, and Japan's window to secure a role in the foldable stack is opening and closing at the same time.




